Indonesia Crypto Tax 2026: Final PPh 22 after PMK 50/2025
Indonesia taxes many crypto disposals through a final withholding tax on transaction value rather than a conventional net capital-gain calculation. PMK 50/2025 changed the rates and removed VAT from the transfer of crypto assets on 1 August 2025. This guide separates the old and new periods, domestic and foreign platforms, and trading from mining.
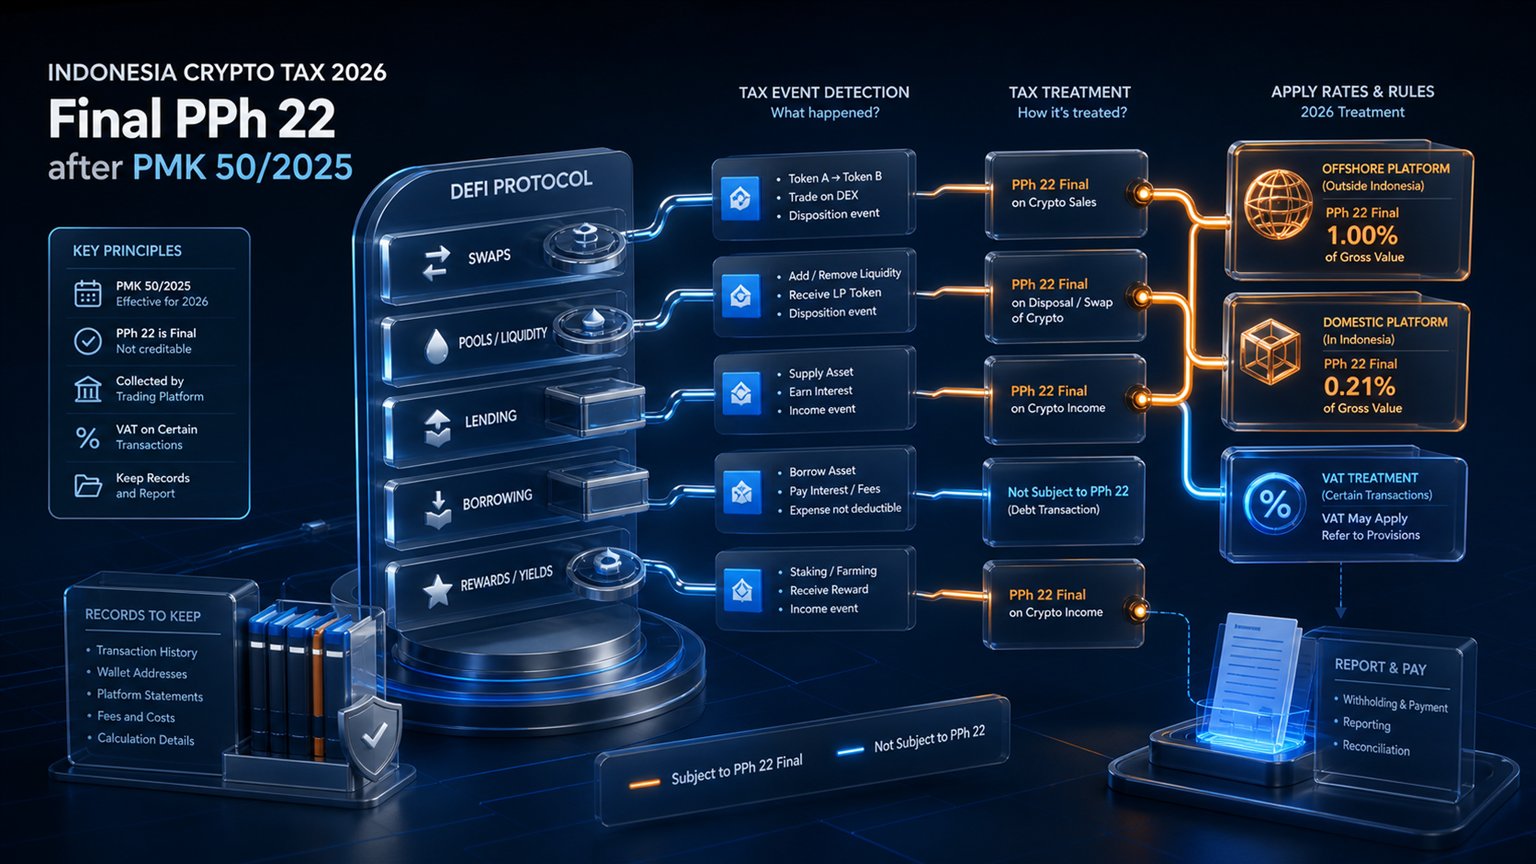
The PMK 50/2025 cutover is the starting point
Prepare Your Crypto Tax Workpapers
Import your transactions, review the results and generate detailed tax workpapers without building the entire calculation manually in spreadsheets.
Start for free →For ordinary crypto sales, Indonesia uses final Income Tax Article 22 (PPh Pasal 22 final) calculated on transaction value. This is structurally different from a country that taxes proceeds minus acquisition cost. The applicable platform and transaction date therefore matter before profit or loss is considered.
| Period and route | Final PPh 22 | VAT on transfer of crypto |
|---|---|---|
| Up to 31 July 2025, approved domestic physical crypto trader | 0.10% of transaction value | Effective 0.11% |
| Up to 31 July 2025, other route | 0.20% of transaction value | Effective 0.22% |
| From 1 August 2025, domestic PAKD/PPMSE | 0.21% of transaction value | Crypto transfer itself not subject to VAT |
| From 1 August 2025, foreign PPMSE route | 1.00% of transaction value | Crypto transfer itself not subject to VAT |
| Domestic operators within Article 13: wallet-only, matching-only or not facilitating trades | 0.21%, paid by the seller | Collector exception does not create a1% rate |
The earlier VAT figures are 0.11% and 0.22%, not 1% and 2%. PMK 68/2022 described them as 1% or 2% of the general VAT rate; treating those multipliers as the effective rates exaggerates the tax tenfold. From 1 August 2025, PMK 50 treats the crypto asset itself like a security for VAT purposes. Platform services and mining verification services can still carry VAT, so “no crypto VAT” is too broad.
Final PPh is based on value, not trading profit
For transactions within this final regime, acquisition cost, fees and a realised trading loss do not reduce the PPh 22 base. A sale for IDR 100 million can therefore attract the same final PPh as another IDR 100 million sale even when one is profitable and the other is not. A FIFO or average-cost ledger remains valuable for economic performance and audit evidence, but it must not be presented as the statutory base for this final transaction-value tax.
This distinction also prevents a misleading “taxable profit” total. A useful Indonesian report should show gross transaction value, applicable rate, tax collected or self-paid, platform status and evidence separately. It may show economic gain or loss in a reconciliation column, clearly labelled as non-controlling for final PPh.
Domestic PAKD, appointed foreign platform or self-payment
A licensed domestic digital financial asset trader (PAKD) normally collects the 0.21% final PPh. A foreign electronic trading system operator may be appointed to collect the 1% rate. Where the foreign operator has not been appointed, PMK 50 places the payment obligation on the seller. The report cannot infer collector status merely from an exchange brand: it should record the legal entity, route, withholding certificate and actual deduction.
Article 13 separately covers operators providing only a wallet, only matching buyers and sellers, or not facilitating crypto trades: the seller self-pays 0.21%. “Not a PAKD collector” therefore is not enough to select1%. For a foreign operator, Article 22 requires seller self-payment where no collector is appointed. Article 21 also retains seller self-payment at 1% if an appointed foreign collector fails to perform the required collection. Check actual compliance and prevent duplicate payment where a valid collection already exists.
- Reconcile every deduction to the platform statement or official withholding evidence.
- Do not assume that a foreign platform collected Indonesian tax.
- Keep IDR conversion evidence for consideration received in fiat or crypto.
- Separate pre- and post-1 August 2025 transactions before aggregating.
Article 12(6) uses the Minister-established exchange rate at the date payment is received for non-rupiah fiat consideration. For swaps and the other covered non-fiat transactions, Article 12(7) provides the Bursa value, operator-system value or a qualifying sale value before the payment deadline, applied consistently. Preserve the selected statutory valuation route, original currency, source amount and date; an annual average exchange rate is not a substitute. Our audit-trail guide explains how original and reconstructed fields should remain distinguishable.
Boundary example: the same sale value, different date or route
Assume an ordinary seller has a transaction value of IDR 100,000,000 and supported acquisition cost of IDR 120,000,000, without any applicable exception. The economic loss of IDR 20,000,000 does not cancel the final transaction-value tax.
| Assumed route and date | Final income-tax calculation | Evidence to reconcile |
|---|---|---|
| Approved domestic route,31 July2025 | IDR 100,000,000 × 0.10% =IDR 100,000 | Old-regime statement and transaction date |
| Domestic PAKD,1 August2025 | IDR 100,000,000 × 0.21% =IDR 210,000 | New-regime collection proof |
| Domestic Article 13 collector exception after cutover | IDR 210,000, self-paid | Legal route and seller payment/report |
| Foreign route after cutover | IDR 100,000,000 × 1% =IDR 1,000,000 | Appointment and actual collection, or seller payment |
A report that retains the July 0.10% rate after 1 August understates the domestic amount by IDR110,000. A report that labels every non-collector “foreign1%” overstates the Article 13 case by IDR790,000. Store the operator's legal entity and status at the event date beside the value, rate, certificate and any self-payment. These figures are final income tax only; the old asset-VAT mechanism and any service VAT are separate checks.
Crypto swaps, spending, mining and DeFi need separate paths
The regulated transaction concept is not limited to cashing out into rupiah. Crypto-to-crypto exchanges and transfers in exchange for goods or services have a transaction value and must not disappear from the PPh working paper. Transfers between wallets owned by the same taxpayer are different: without a counterparty disposal they should normally be identified as internal movements, subject to evidence of common ownership.
Mining is not just another exchange sale. The Directorate General of Taxes explains that PMK 50 moved miners to ordinary income-tax rates from tax year 2026, while verification services retain a VAT mechanism. Rewards, staking and DeFi receipts should be classified by their legal and economic function; an exchange event label alone does not establish that the final trading rate applies.
Derivatives likewise require contract-level review. A futures close P&L is not the gross sale of the referenced token, and open positions or snapshots are not realised tax results. The report should retain realised close results, funding and fees separately and flag an unresolved contract rather than forcing it through the spot PPh formula. See also our DeFi tax data guide.
What an Indonesian crypto tax working paper should contain
- Confirm tax residence and reporting year.
- Identify the platform legal entity and its domestic, foreign and collector status.
- Split transactions at 1 August 2025.
- Value each taxable transaction in IDR with an auditable rate.
- Apply the statutory rate to gross transaction value.
- Reconcile tax withheld, tax self-paid and missing evidence.
- Keep wallet transfers, mining, rewards, DeFi and derivatives in distinct schedules.
A software report is supporting documentation, not proof that every foreign platform satisfied Indonesian collection and filing obligations. The taxpayer should preserve exchange statements, wallet records, invoices, withholding documents and year-end holdings. Compare this transactional system with the gain-based regimes described in our Hong Kong guide and India guide.
Frequently asked questions
Does Indonesia tax only profitable crypto trades?
No. Final PPh 22 is generally calculated on transaction value, so acquisition cost and a loss do not reduce its base.
Is the old crypto VAT rate 1%?
No. The effective approved-platform rate was 0.11%; the rule used 1% of the general VAT rate. The corresponding other-route effective rate was 0.22%.
Is crypto free from VAT after 1 August 2025?
The transfer of the crypto asset is not subject to VAT under PMK 50. Related platform and mining-verification services can still be subject to VAT.
Does an offshore exchange always collect the 1% tax?
No. Appointment and actual collection must be verified. If the platform is not an appointed collector, the seller can have a self-payment obligation.
Can opening positions be counted as taxable derivative profit?
No. Open events and snapshots document a position; realised close P&L, funding and fees require their own contract-based analysis.
Official sources
- Directorate General of Taxes: PMK 50/2025
- DGT: crypto tax before and after PMK 50
- DGT: PMK 68/2022 text and earlier rates
Ministry of Finance: PMK50/2025 full official PDF, particularly Articles 12–13 and20–22, supplies the valuation and collector/self-payment distinctions used in the example.
Reviewed 9 October 2026. This guide is general information and not Indonesian tax advice.
Related Resources
Generate Your Crypto Tax Report
Import your transactions, review the results and generate a detailed PDF report with a transaction-level audit trail.
Start for free →Disclaimer: This article is for general informational purposes only and does not constitute tax advice. For individual tax advice, consult a licensed tax professional.