Israel Crypto Tax 2026: Capital Gains, Form 1399 and Business Activity
Israel Tax Authority Circular 5/2018 treats decentralized virtual currency as an asset rather than currency. A private investor will therefore commonly calculate a 25% real capital gain on disposal, while activity amounting to a business follows ordinary income rules. Filing, surtax, mining and transaction classification require more care than the headline rate suggests.
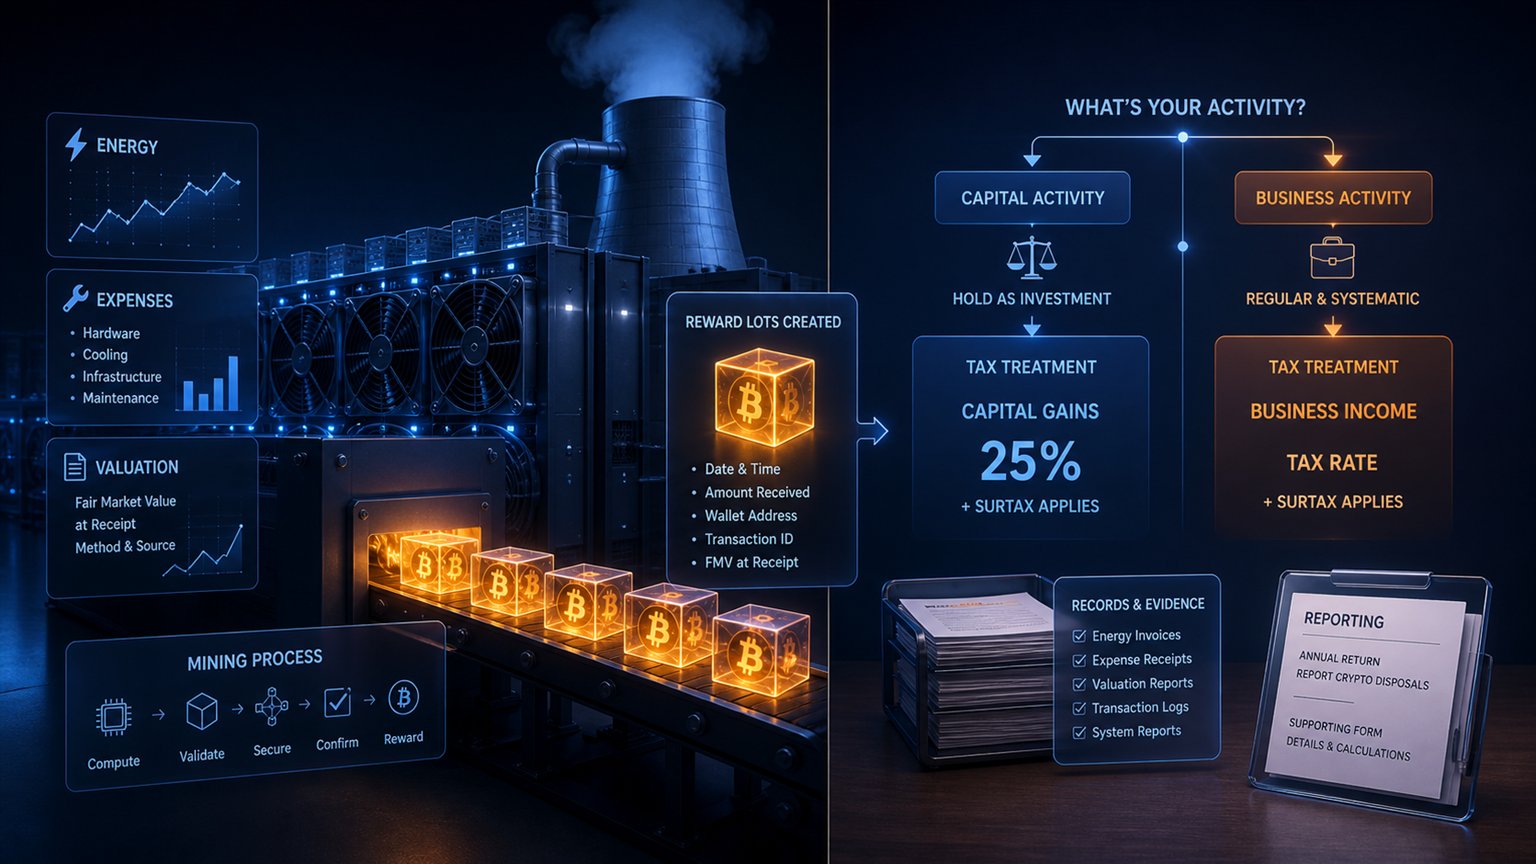
Circular 5/2018 treats virtual currency as an asset
Prepare Your Crypto Tax Workpapers
Import your transactions, review the results and generate detailed tax workpapers without building the entire calculation manually in spreadsheets.
Start for free →The Israel Tax Authority’s Circular 05/2018 states that a decentralized means of payment commonly called a virtual currency is an “asset” for Income Tax Ordinance purposes. It is not treated as legal currency or foreign currency merely because market participants call it money. A sale or exchange can therefore create a capital gain or loss.
For a private individual holding the asset as an investment, the common headline rate is 25% on the real capital gain. The result is not 25% of gross sale proceeds. Proceeds, documented acquisition cost and permitted expenses must be calculated in shekels. Crypto-to-crypto exchange can also be a disposal: remaining inside a blockchain ecosystem does not defer the event automatically.
| Facts | Likely route | Report output |
|---|---|---|
| Private investment disposal | Capital-gains rules, commonly 25% | Real gain/loss and Form 1399 support |
| Activity constitutes a business | Ordinary business income | Revenue, expenses and accounting schedule |
| Mining business | Business treatment under Circular 5/2018 | Income and operating-cost records |
| Company-held crypto | Corporate taxation and accounts | Company reporting, not private 25% shortcut |
The 25% rate is not a universal crypto rate
Circular 5/2018 distinguishes investment from business activity. Whether frequent buying and selling amounts to a business is a factual question under the ordinary Israeli tests: frequency, holding period, expertise, organisation, financing, scale and commercial character can all matter. Transaction count alone should neither force business status nor guarantee private status.
Once activity is classified as business, ordinary marginal income-tax treatment replaces the private capital-gain shortcut and National Insurance or VAT issues may also arise. The circular specifically treats mining activity as business activity. A software engine should therefore ask for the actual profile and retain the classification decision instead of allowing the user to “choose the lower rate”.
Staking, lending, airdrops, liquidity incentives and DeFi contracts do not all create the same legal entitlement. A receipt may be compensation for service, yield, a distribution or part of a capital transaction. The imported event name is evidence, not a legal conclusion. Each receipt needs a shekel value at the relevant time and an explanation of the economic cause.
Form 1399 is relevant to virtual-currency disposals
The Tax Authority’s official asset-sale service explicitly lists virtual currencies among the assets reportable through Form 1399 under section 91. It also says losses from asset sales must be reported. A detailed transaction schedule should support the figures because an annual net P&L without proceeds, cost, date and asset identification is not enough to reproduce the calculation.
The Tax Authority’s published service requires an individual asset-sale report within 30 days of the sale, with the resulting capital-gains tax paid alongside submission. Active crypto accounts can generate hundreds of disposals, but a blog or tax engine should not promise that one annual consolidated form is always accepted unless that treatment has been confirmed for the taxpayer. The defensible workflow is to prepare transaction-level Form 1399 support and confirm the filing mechanics with the assessing office or adviser.
- Do not replace Form 1399 with a securities-withholding annex merely because the exchange resembles a broker.
- Record realised gains and losses, not just profitable disposals.
- Keep the annual return consistent with notices and payments already submitted.
- Retain exchange, wallet and bank evidence for the shekel conversion.
Mas Yesef can increase the effective tax on large gains
The basic 25% capital-gains rate is not always the final rate. Israel’s additional tax on high income (Mas Yesef) can apply when taxable income exceeds the annual statutory threshold. For tax year 2025, Tax Authority implementation guidance uses a threshold of ILS 721,560 and explains the 3% additional tax plus the additional 2% layer for qualifying capital-source income above the relevant threshold.
The personal threshold and the composition of total income sit outside a crypto-only dataset. A report should therefore show the crypto capital result and a surtax review flag, not automatically assert a final personal liability. It must also use the threshold for the relevant tax year rather than carrying the 2025 number into later years unchanged.
VAT, derivatives and internal movements
Circular 5/2018 discusses VAT according to the taxpayer’s role and activity. A private investor whose activity does not amount to a business is not the same as an exchange, miner or business dealer. VAT status cannot be inferred solely from a capital-gain calculation.
Crypto derivatives require contract analysis. A close-long or close-short line with realised broker P&L can be a realised contract result, whereas open-long, open-short and position-snapshot records generally document exposure rather than a second taxable profit. Funding and fees should remain separate. If the legal character of the contract is not established, the report should mark the result for review instead of treating the referenced token as if it had been sold.
Transfers between a taxpayer’s own wallets normally document a change of custody rather than a disposal. A transfer to another beneficial owner, payment for goods or swap is different. Wallet ownership and transaction hashes must be preserved so that cost is carried forward only where ownership truly remains unchanged.
How to prepare an audit-ready Israeli crypto report
- Confirm Israeli residence and private, business or company profile.
- Import every exchange and wallet so internal movements can be reconciled.
- Calculate each disposal in ILS with timestamped value evidence.
- Separate capital disposals, business income, mining, rewards and derivative contracts.
- Prepare transaction-level Form 1399 support and reconcile prior payments.
- Flag high-income surtax without assuming the taxpayer’s non-crypto income.
- Keep missing basis or contract status visible as an unresolved item.
A zero cost entered only because opening data are missing can overstate a gain and is not a verified tax basis. The position should remain “not calculable” while the rest of the report completes. Reconstructed dates or prices must be labelled. See our tax-data error guide and DeFi audit-trail guide.
Do not import a neighbouring country’s shortcut. The UAE guide follows a very different natural-person/business framework, while the India guide applies its own VDA regime.
Worked ILS reconciliation: proceeds, real gain and payments
Assume a private investor disposes of an investment lot for ILS 60,000. Documented original acquisition cost is ILS 40,000, including purchase expenses already recorded there; a separate permitted sale expense is ILS 200. For this simplified illustration, assume the completed real-gain calculation has no inflation component or other adjustment, and there are no losses or special reliefs. The real gain is then 60,000 − 40,000 − 200 = ILS 19,800, and the base tax at 25% is ILS 4,950.
The net cash receipt is ILS 59,800. That amount is not the gain, and neither 25% of gross proceeds nor a dollar-denominated exchange profit reproduces the Israeli calculation. In an actual case, retain the acquisition/disposal dates, ILS conversion and any required real-gain adjustments. If the consideration was other crypto rather than cash, keep its ILS market value and incoming acquisition record as well as the outgoing asset-sale schedule.
The official Form 1399 service also treats the notice as an annex to an individual's annual return, Form 1301. For an online annual return, the sale is included there in addition to the earlier notice. Preserve the ILS 4,950 payment receipt as a payment already made when reconciling the annual liability; entering the same event in the annual return must not create an unexplained second payment. Further personal tax or a revised assessment can still change the final balance.
Surtax example: total income and capital income are different bases
Using the 2025 threshold expressly stated in implementation instruction 05/2025, compare two taxpayers with no relevant deductions or reliefs. These are illustrative annual surtax calculations before return rounding, not a 2026 threshold forecast.
| 2025 taxable income | 3% layer on total income above ILS 721,560 | 2% layer on capital-source income above ILS 721,560 |
|---|---|---|
| Salary/business ILS 800,000 plus qualifying private capital gain ILS 600,000 | (1,400,000 − 721,560) × 3% = ILS 20,353.20 | Zero: capital income alone is below the threshold |
| Only qualifying private capital gain ILS 900,000 | (900,000 − 721,560) × 3% = ILS 5,353.20 | (900,000 − 721,560) × 2% = ILS 3,568.80 |
The second scenario has ILS 8,922 of surtax in this simplified calculation, alongside ILS 225,000 base capital-gains tax. Applying a flat 30% to all ILS 900,000 would incorrectly charge both surtax layers below their thresholds. Conversely, the first scenario shows why high salary does not by itself make all capital income subject to the extra 2% layer. Income classification and the relevant year's parameters need their own reconciliation.
The Tax Authority's English asset-sale service confirms the notice, payment and annual-return relationship. Tax residence and qualifying new-immigrant or returning-resident reliefs should also be checked before applying the ordinary private-investor calculation; relief for a particular income source is not an exemption for every crypto disposal.
Frequently asked questions
Is every Israeli crypto gain taxed at 25%?
No. 25% is the common private capital-gain rate. Business income, companies, surtax and special facts can lead to a different outcome.
Is a crypto-to-crypto swap reportable?
It can be a disposal because virtual currency is treated as an asset, even when no fiat is received.
Does Form 1399 cover virtual currency?
Yes. The Tax Authority’s official asset-sale service explicitly includes virtual currencies among reportable assets.
Can an annual consolidated Form 1399 always replace transaction notices?
Do not assume so. Prepare detailed support and confirm the accepted filing method with the assessing office or adviser.
Are opening futures positions taxable profit?
They normally document exposure rather than realised P&L. Closed results, funding and fees need separate contract-based classification.
Official sources
- Israel Tax Authority: Income Tax Circular 05/2018
- Israel Tax Authority: asset-sale reporting and Form 1399
- Israel Tax Authority: 2025 additional-tax implementation guidance
- State Comptroller: taxation of digital currencies
Reviewed 9 October 2026. This guide is general information and not Israeli tax advice.
Related Resources
Generate Your Crypto Tax Report
Import your transactions, review the results and generate a detailed PDF report with a transaction-level audit trail.
Start for free →Disclaimer: This article is for general informational purposes only and does not constitute tax advice. For individual tax advice, consult a licensed tax professional.