Crypto Tax by State in 2026: Residency, Sourcing, and Filing
Federal crypto tax rules apply nationwide, but the state layer depends on where you are resident, where income is sourced, and whether your activity is investment or business income. A state with no broad individual income tax does not erase federal tax, and moving after a profitable sale normally does not move the already-realized gain.
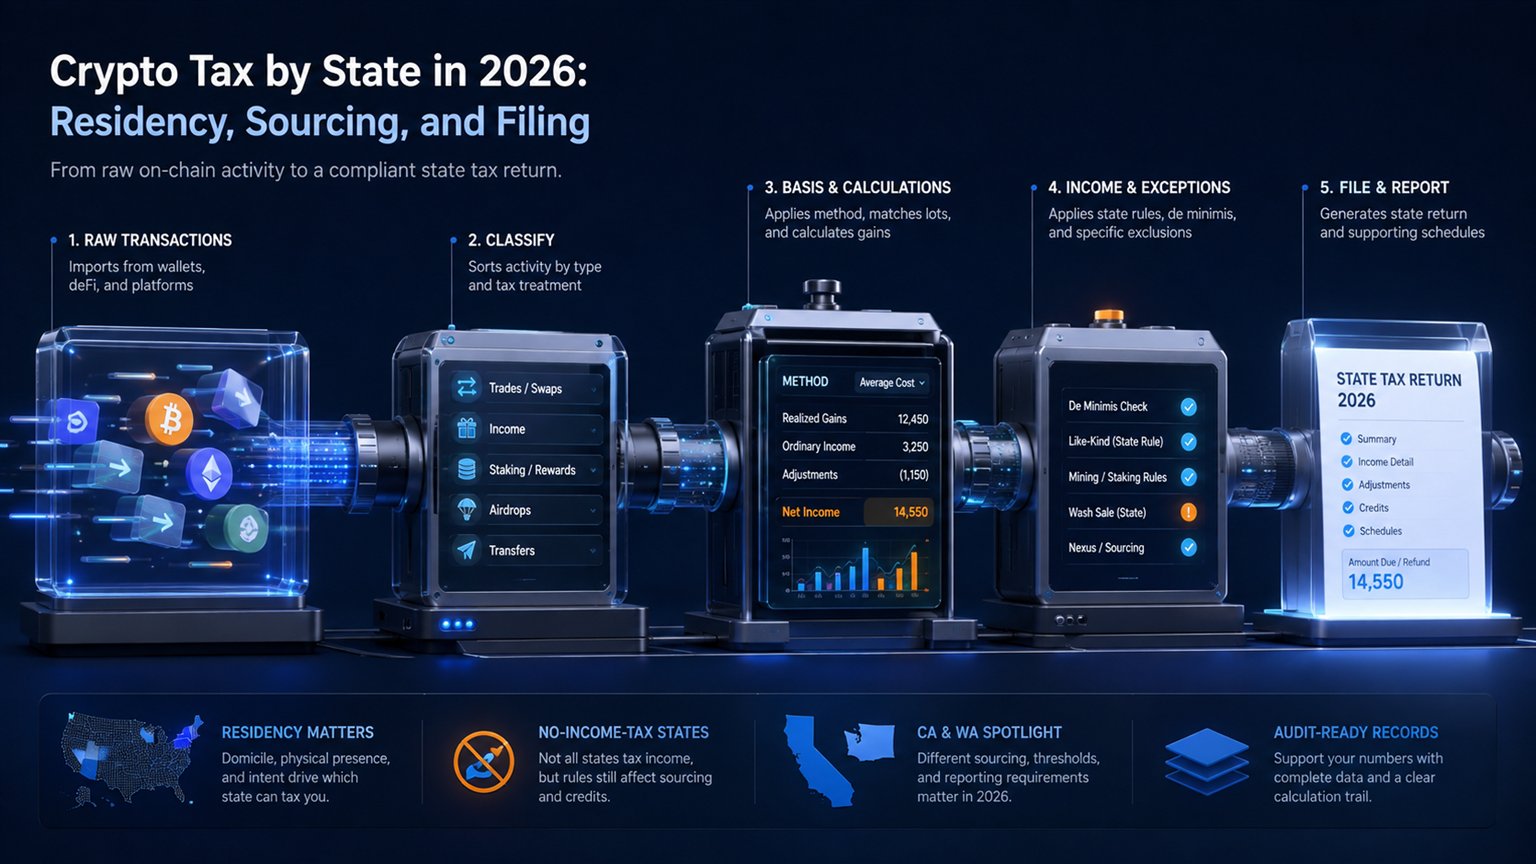
Federal crypto tax remains the starting point
Prepare Your Crypto Tax Workpapers
Import your transactions, review the results and generate detailed tax workpapers without building the entire calculation manually in spreadsheets.
Start for free →The IRS treats digital assets as property. Selling crypto for dollars, exchanging one digital asset for another, spending crypto, and many other dispositions can create federal gain or loss. Compensation, mining, and staking rewards can create ordinary income. These rules do not disappear because a taxpayer lives in a state without an individual income tax.
For capital assets, calculate proceeds, adjusted basis, holding period, and gain or loss transaction by transaction. Dispositions generally flow through Form 8949 and Schedule D. The 2025 Form 8949 introduced digital-asset boxes G/H/I for short-term transactions and J/K/L for long-term transactions. See our Form 8949 crypto guide before mapping broker data.
State tax follows residency and sourcing, not the exchange logo
A Coinbase, Kraken, or offshore exchange account does not by itself determine which state may tax the result. A full-year resident usually reports income under the resident-state rules. A part-year resident may need to divide income between periods. A nonresident can still have state-source income, especially from a trade or business conducted in the state.
Digital assets make sourcing difficult because wallet location is not a physical address and a decentralized protocol has no single counterparty office. The answer may depend on domicile, residence, business activity, and the character of the income. Keep evidence of the transaction date, residence period, business location, and the state's instructions used for the return.
| Question | Why it matters | Evidence to retain |
|---|---|---|
| Where were you domiciled? | Often determines resident filing | Home, driver's license, voting, family and work facts |
| When did residency change? | Separates full-year and part-year periods | Lease, closing, travel and employment records |
| Investment or business? | Can change sourcing and deductions | Trading pattern, books, business records |
| When was gain realized? | Locks the transaction into a tax period | Order fills and on-chain confirmations |
Which states have no broad individual income tax?
As of 2026, Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, and Wyoming do not impose a broad state individual income tax. New Hampshire's former Interest and Dividends Tax was repealed for taxable periods beginning after December 31, 2024. This list is not a promise of zero state or local tax: business, franchise, gross-receipts, sales, property, or local taxes can still apply.
Florida's Department of Revenue confirms that Florida has no personal income tax and no individual capital gains tax. That still leaves federal income tax and reporting intact. A taxpayer operating a crypto business through an entity also needs a separate entity-level analysis.
California and Washington show why headlines are misleading
California
California does not provide a special lower rate for capital gains. Its Franchise Tax Board states that capital gains are taxed as ordinary income. Federal and California basis can also differ, so a taxpayer should not copy the federal total into a state return without checking California adjustments.
Washington
For the 2026 tax year, Washington has no broad wage income tax, but it imposes a capital gains excise tax on qualifying net long-term gains allocated to the state. From tax year 2025, the first $1 million of taxable Washington capital gains after applicable deductions is taxed at 7%; the excess is taxed at 9.9%. Crypto is not a blanket exemption. The $1 million rate boundary is not a gross sale-proceeds threshold.
Washington example: apply the deduction before the rate tiers
Assume a single Washington-domiciled investor has $1.4 million of Washington-allocated, nonexempt net long-term investment gains in 2025, after eligible losses, with no other deduction or credit. The Department of Revenue publishes a $278,000 standard deduction for 2025. Taxable Washington capital gains are therefore $1,400,000 − $278,000 = $1,122,000. The illustrative state tax is $1,000,000 × 7% + $122,000 × 9.9% = $70,000 + $12,078 = $82,078.
This is a 2025 calculation for a return due in 2026. The official indexed-amount table reviewed on October 9, 2026 lists amounts through 2025; use the subsequently published 2026 amount for a 2026 return rather than reusing $278,000 or estimating inflation. Federal tax, other Washington adjustments and individual credits are outside the example. A married couple does not automatically receive two full standard deductions.
A separate Washington income tax starts in a later year
Chapter 238, Laws of 2026, was approved March 30, 2026. Section 201 provides for a 9.9% income tax beginning January 1, 2028, with a $1 million standard deduction and statutory adjustments and credits. It is enacted legislation, not an additional 2026 income tax. Investors planning a later move should revisit those rules; simply adding its rate to the current capital gains rate does not apply the law correctly.
Washington filing generally follows the federal due date, but a federal filing extension does not extend the payment deadline. Review the Department of Revenue's current deduction, exclusions, credits, and allocation guidance for the actual tax year.
Moving before or after a crypto sale
A genuine change of domicile requires facts, not only a mailing address. States examine the home, family, employment, time spent, licenses, registrations, and intent. A sale completed while still resident in the old state is not normally transformed into a new-state transaction by moving later.
- Record the exact date and time of every disposition.
- Keep evidence supporting the old and new residency periods.
- Check part-year returns in both states where required.
- Review whether deferred payments, installment sales, or business income have special sourcing rules.
- Do not assume a VPN, wallet address, or exchange jurisdiction changes domicile.
California-to-Florida example: separate two disposal dates
Suppose a genuine, documented domicile change occurs on July 1, 2026. While still a California resident, an investor sells one investment lot on June 10 for $50,000 with $30,000 adjusted basis: $20,000 gain. A different lot is sold on August 15 for $45,000 with $35,000 basis: $10,000 gain. Assume both are passive investments, all costs are already included, and the later gain has no California business or other source connection. The federal ledger records both gains, totaling $30,000. California's part-year analysis includes the $20,000 resident-period gain; moving later does not erase it. The $10,000 later gain requires the nonresident sourcing analysis and does not create Florida personal income tax.
Retain evidence establishing July 1 as the real change date and use the California Form 540NR instructions for the full calculation. California can use worldwide income to determine the applicable rate before apportioning the tax, so excluding a non-California-source item from the taxed income does not mean it is absent from every return field. Employment, business income, installment payments or an unsupported domicile change can change the example.
A defensible state crypto filing workflow
- Build one complete federal ledger across exchanges and wallets.
- Reconcile broker Forms 1099-DA without duplicating imported sales.
- Classify capital dispositions, ordinary income, business activity, and derivatives.
- Attach residency periods and potential source state to each relevant income item.
- Start from the state return instructions and identify federal conformity differences.
- Reconcile federal Form 8949/Schedule D totals to every state adjustment.
- Save calculations, source exports, state instructions, and residency evidence.
Our U.S. capital gains guide explains the federal calculation, while the 1099-DA guide covers broker reconciliation. State tax is an additional layer, not a replacement ledger.
Frequently asked questions
Does living in Florida eliminate crypto tax?
It eliminates Florida personal income tax, not federal tax. Business and other taxes can still require separate review.
Is Washington a no-tax state for crypto?
Not categorically. Washington can tax qualifying net long-term capital gains above its annual deduction.
Does California use the federal long-term capital gain rate?
No. California states that it taxes capital gains as ordinary income and has no special lower state rate.
Can I move after selling and avoid the old state's tax?
A later move generally does not change where you were resident when the gain was realized. Part-year and sourcing rules must be applied to the facts.
Which exchange location controls state tax?
Exchange location alone is generally not the controlling fact. Residency, domicile, source, business activity, and state law matter.
Official sources
- IRS digital asset transaction FAQs
- California FTB: capital gains and losses
- Washington DOR: capital gains tax
- Washington DOR: published indexed deductions
- Washington DOR: 7% and 9.9% tiers from 2025
- Washington: Chapter 238, Laws of 2026, sections 201, 205 and 314
- California FTB: part-year and nonresident return instructions
- Florida DOR: individual capital gains tax
- New Hampshire DRA: I&D tax repeal
Reviewed October 9, 2026. State rules and inflation-adjusted thresholds can change; use the official instructions for the return year and your residency facts.
Related Resources
Generate Your Crypto Tax Report
Import your transactions, review the results and generate a detailed PDF report with a transaction-level audit trail.
Start for free →Disclaimer: This article is for general informational purposes only and does not constitute tax advice. For individual tax advice, consult a licensed tax professional.